
What Is a Credit Score? How It Works and How to Improve It
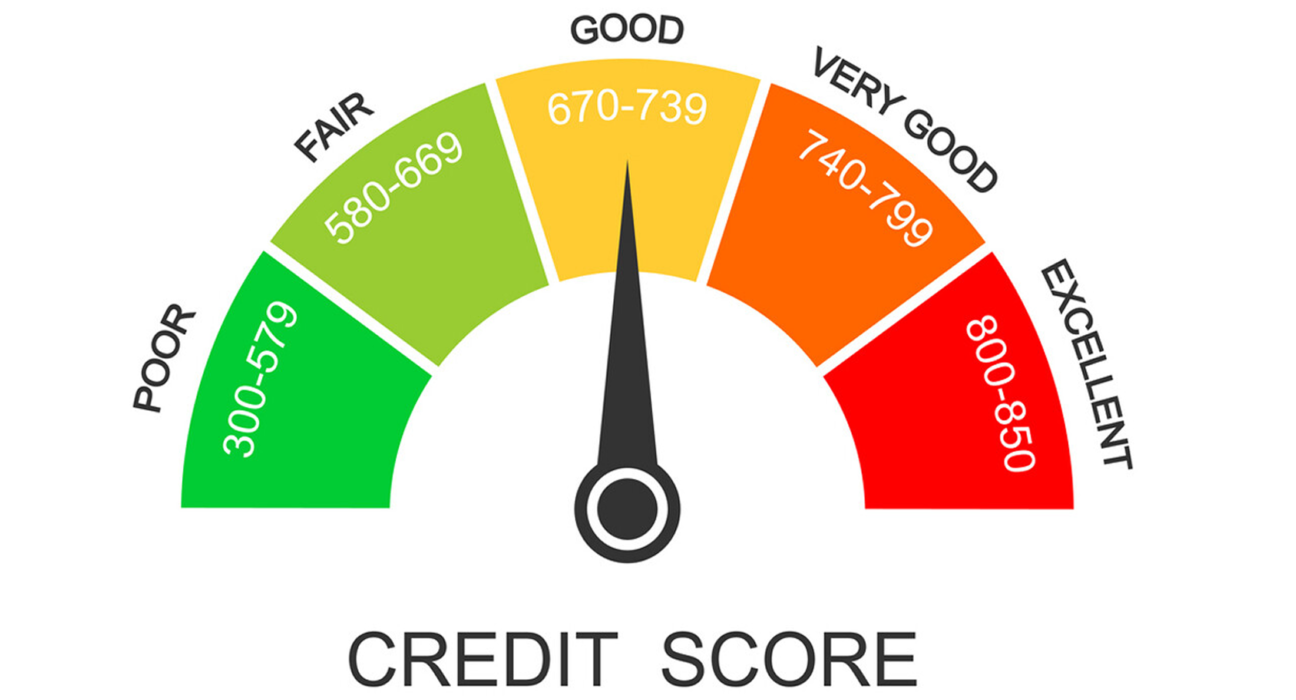
A credit score is one of the most important numbers in personal finance.
It can influence whether you qualify for certain loans or credit products, the terms you may receive, and how lenders assess your creditworthiness.
Yet many people don’t fully understand what a credit score actually represents or how their financial behavior can affect it.
The good news is that the basic concept is fairly simple.
A credit score is a numerical representation of information in your credit history. It helps lenders assess how you have handled credit in the past and how likely you may be to manage future borrowing responsibly.
Here’s what you need to know.
What Is a Credit Score?
A credit score is a number calculated from information contained in your credit history.
Credit reporting systems collect information about your borrowing and repayment activity, and scoring models use certain aspects of that information to calculate a score.
Depending on the country, credit scoring systems and score ranges can differ.
In general, a stronger credit profile suggests a lower perceived lending risk, while a weaker profile may make borrowing more difficult or expensive.
Why Does a Credit Score Matter?
Lenders want to understand the risk involved in providing credit.
Before approving an application, they may consider factors such as:
- Credit history
- Existing debt
- Income
- Repayment behavior
- Current credit obligations
- Other information included in the application
A credit score can be one part of that assessment.
A stronger credit profile may make it easier to qualify for certain financial products, although approval is never guaranteed based on a score alone.
How Is a Credit Score Calculated?
Credit scoring models generally examine different aspects of your credit behavior.
The exact formula varies by scoring system, lender, and country.
Common factors can include:
Payment History
Have you paid your credit obligations on time?
Consistently making payments by their due dates can help demonstrate responsible credit management.
Late or missed payments can negatively affect your credit profile.
Amount of Debt
The amount you currently owe can also matter.
Carrying significant outstanding balances may indicate a higher level of borrowing risk, depending on the type of credit involved.
Credit Utilization
For revolving credit such as credit cards, lenders and scoring systems may consider how much of your available credit you’re using.
For example, if a card has a limit of ₹1,00,000 and the outstanding balance is ₹20,000, the utilization is:
₹20,000 ÷ ₹1,00,000 = 20%
Lower utilization is generally viewed more favorably by many scoring models, although there isn’t one universal percentage that guarantees a particular score.
Length of Credit History
The amount of time you’ve had credit accounts can also be relevant.
A longer history can provide more information about how you’ve managed credit over time.
Types of Credit
Your credit profile may include different types of borrowing, such as:
- Credit cards
- Personal loans
- Auto loans
- Home loans
- Other credit facilities
Having different types of credit isn’t automatically better. Responsible management is generally more important than simply opening multiple accounts.
Recent Credit Applications
Applying for multiple credit products within a short period can sometimes affect your credit profile.
Lenders may interpret frequent applications as a potential sign that someone is seeking significant additional credit.
Credit Score vs Credit Report
These two terms are often confused.
Credit Report
A credit report contains information about your credit activity and accounts.
It may include:
- Credit accounts
- Outstanding balances
- Payment history
- Credit inquiries
- Account status
- Other relevant credit information
Credit Score
A credit score is a numerical calculation based on information from your credit history.
Think of it this way:
Credit report = detailed record
Credit score = numerical summary used for risk assessment
You should understand both rather than focusing only on the score.
What Is a Good Credit Score?
There is no single universal definition of a “good” credit score.
Score ranges vary depending on:
- Country
- Credit bureau
- Scoring model
- Financial institution
For that reason, you should always understand which scoring system you’re looking at before interpreting the number.
A score should also be considered alongside the broader information in your credit report.
What Can Lower Your Credit Score?
Several behaviors can potentially hurt your credit profile.
These may include:
- Missing payments
- Making payments late
- Taking on excessive debt
- Maintaining high revolving balances
- Applying for multiple credit accounts in a short period
- Defaulting on credit obligations
- Closing accounts without understanding the consequences
Not every action affects every scoring model in the same way.
That’s why reviewing your actual credit report can be more useful than guessing what happened to your score.
How to Improve Your Credit Score
Improving your credit profile usually takes time.
There is rarely a legitimate instant solution.
1. Pay Bills on Time
Consistent repayment is one of the most important habits you can develop.
Set reminders or automatic payments where appropriate so you don’t accidentally miss due dates.
2. Keep Debt Manageable
Avoid borrowing more than you can comfortably repay.
A high income doesn’t automatically create a strong credit profile if borrowing and repayments aren’t managed responsibly.
3. Monitor Your Credit Report
Check your credit information periodically.
Look for:
- Incorrect personal information
- Accounts you don’t recognize
- Incorrect payment records
- Unexpected inquiries
- Incorrect outstanding balances
If you identify an error, contact the relevant credit bureau or lender and follow its dispute process.
4. Avoid Unnecessary Credit Applications
Don’t apply for multiple credit products simply because they’re available.
Before applying, consider whether you actually need the credit and whether you can comfortably manage the resulting payments.
5. Keep Track of Credit Card Balances
If you use credit cards, monitor your balances rather than waiting until the payment deadline to discover how much you’ve spent.
A simple spending limit can help prevent balances from becoming difficult to manage.
6. Give Your Credit History Time
Building a stronger credit profile is usually a long-term process.
Consistent financial behavior over time provides more evidence of responsible credit management.
Does Checking Your Own Credit Score Hurt It?
Generally, checking your own credit information is different from applying for new credit.
Depending on the system being used, there can be a distinction between:
Soft inquiries: Checks that generally don’t affect your score in the same way as applications for new credit.
Hard inquiries: Credit checks associated with certain applications for new borrowing and may affect your credit profile.
The exact rules depend on the country and scoring system.
Can You Have a Credit Score Without a Credit Card?
Yes.
A credit card is only one possible form of credit.
Depending on the country and reporting system, other credit accounts may contribute to your credit history.
However, having no credit history can sometimes make it difficult for lenders to assess your borrowing behavior.
That’s different from having a poor credit history.
Credit Score vs Income
A high income does not automatically mean you have a high credit score.
Income and credit history measure different things.
Income helps indicate your ability to earn money and potentially repay debt.
Credit history provides information about how you’ve handled credit obligations.
Someone with a high income can have poor credit management, while someone with a more modest income can have a strong repayment history.
Lenders may consider both when evaluating applications.
Can You Improve a Poor Credit Score Quickly?
Be cautious of anyone promising an instant credit-score transformation.
There are no shortcuts that can erase legitimate negative information simply because you want a higher score.
The most reliable approach is to:
- Identify what is hurting your credit profile.
- Correct inaccurate information.
- Pay obligations on time.
- Reduce excessive debt.
- Avoid unnecessary new borrowing.
- Maintain responsible habits over time.
Improvement can take time, particularly when negative information is accurate.
How Long Does It Take to Build Credit?
There is no single timeline that applies to everyone.
It depends on factors such as:
- Existing credit history
- Payment behavior
- Amount of debt
- Type of accounts
- Negative information
- Scoring model
Someone with a short credit history may need time to establish a track record, while someone rebuilding after missed payments may need longer.
Consistency matters more than trying to change the score overnight.
Common Credit Score Myths
Myth 1: Checking Your Own Score Always Hurts It
Checking your own score is generally different from a lender performing a credit check during an application.
Myth 2: Carrying a Credit Card Balance Improves Your Score
You generally don’t need to pay interest just to demonstrate responsible credit use.
Responsible repayment is more important than deliberately carrying debt.
Myth 3: Closing Every Credit Card Is Always Better
Closing an account can have different effects depending on your overall credit profile.
Consider the broader consequences before closing an established account.
Myth 4: You Only Have One Credit Score
Different scoring models and credit reporting systems can produce different scores.
The number you see from one source may not be identical to the number used by another lender.
Myth 5: A Credit Score Determines Everything
A credit score is important, but lenders may consider many other factors.
Income, existing obligations, employment, loan amount, and other information can also influence a lending decision.
Simple Habits for Better Credit Management
You don’t need a complicated financial system.
A few consistent habits can make a significant difference:
| Habit | Why It Helps |
|---|---|
| Pay on time | Builds a consistent repayment record |
| Monitor balances | Helps prevent excessive debt |
| Review credit reports | Can help identify errors |
| Limit unnecessary applications | Reduces avoidable credit inquiries |
| Borrow within your means | Keeps repayments manageable |
| Track existing debts | Gives you a clearer financial picture |
Final Thoughts
A credit score isn’t a measure of your overall financial worth.
It’s a tool used to evaluate aspects of your credit history and potential borrowing risk.
The best way to build a healthy credit profile is not to chase a particular number. Instead, focus on responsible financial habits: pay on time, keep debt manageable, monitor your credit information, and only borrow when you have a realistic plan for repayment.
Over time, consistent behavior can create a stronger credit history and give you a better financial foundation.
Financial Disclaimer: This article is provided for general educational purposes only and does not constitute financial, credit, lending, or investment advice. Credit scoring systems and lending practices vary by country and financial institution. Check with the relevant credit bureau or financial provider for information specific to your situation.