
How to Save Money: 15 Simple Ways to Reduce Your Expenses
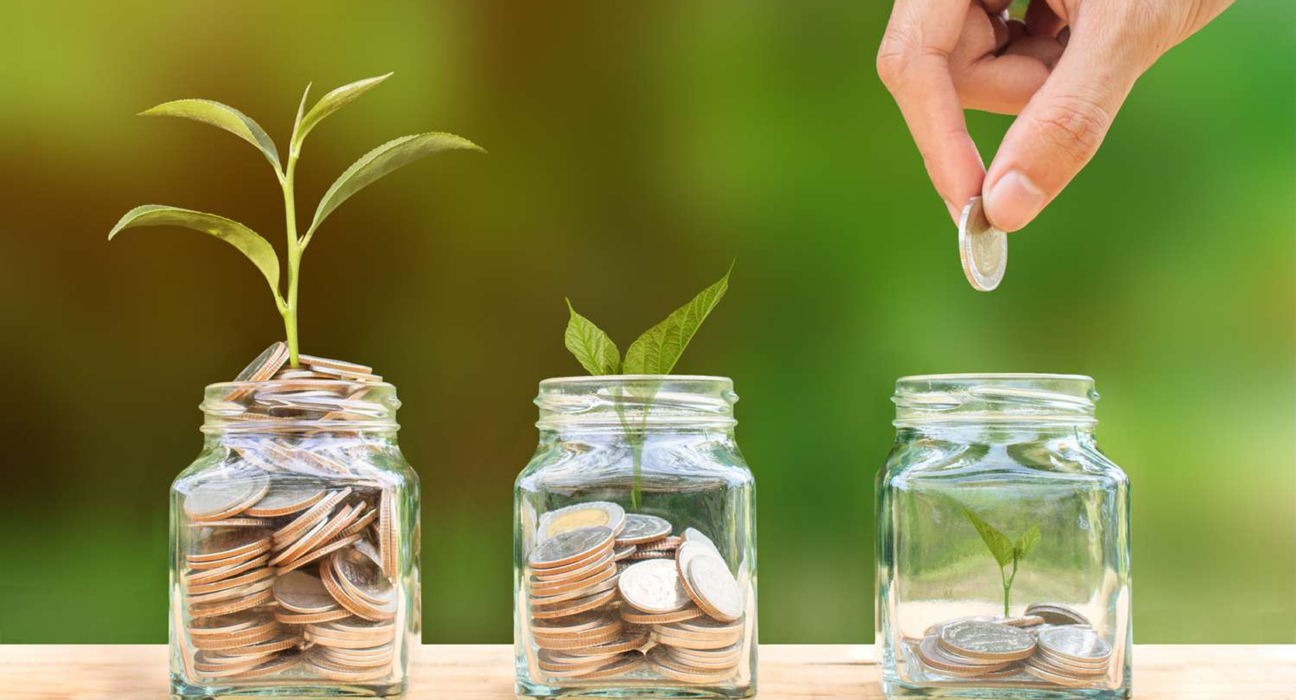
Saving money can seem difficult when everyday expenses continue to increase.
Rent, groceries, transportation, subscriptions, entertainment and unexpected costs can quickly consume a large part of your income. However, saving does not always require making dramatic lifestyle changes.
Small improvements in the way you manage your money can add up over time.
The key is to understand where your money goes, identify unnecessary expenses and create a system that makes saving easier.
Here are 15 practical ways to save money and build better financial habits.
1. Create a Monthly Budget
The first step toward saving money is understanding your income and expenses.
A simple monthly budget can show you:
- How much money you earn
- How much you spend
- Where most of your money goes
- Which expenses are essential
- Where you may be overspending
You do not need complicated software to start.
A spreadsheet, budgeting application or simple notebook can be enough.
Divide your expenses into categories such as housing, food, transportation, entertainment, subscriptions and savings.
Once you can see where your money is going, it becomes easier to make decisions.
2. Track Your Spending
A budget tells you what you plan to spend.
Tracking tells you what you actually spend.
Small purchases can easily go unnoticed.
A coffee here, a food delivery there and a few online purchases may not seem significant individually, but repeated expenses can become substantial over a month.
Try tracking every expense for at least a few weeks.
You may discover spending patterns you were not aware of.
3. Separate Needs From Wants
One of the simplest ways to control spending is to distinguish between things you need and things you want.
Needs may include:
- Housing
- Basic food
- Utilities
- Transportation
- Essential healthcare
- Necessary insurance
Wants may include:
- Entertainment
- Restaurant meals
- New gadgets
- Designer clothing
- Unnecessary subscriptions
- Impulse purchases
This does not mean you should eliminate everything you enjoy.
Instead, understanding the difference helps you decide where your money should go first.
4. Automate Your Savings
Saving becomes easier when you do not have to make the decision every month.
Consider setting up an automatic transfer from your primary account to a dedicated savings account.
The transfer can happen shortly after you receive your income.
Even a relatively small amount can help establish a consistent saving habit.
The important part is consistency rather than choosing an amount that is difficult to maintain.
5. Build an Emergency Fund
An emergency fund is money set aside for unexpected expenses.
Examples include:
- Emergency travel
- Major repairs
- Unexpected bills
- Temporary loss of income
- Urgent household expenses
Without emergency savings, unexpected costs may force you to rely on credit cards or loans.
The amount you need depends on your income, expenses and personal circumstances.
Building the fund gradually can make the goal feel more manageable.
6. Review Your Subscriptions
Subscriptions can be easy to forget because payments are often automatic.
Look through your recurring expenses and identify services you rarely use.
These might include:
- Streaming services
- Fitness memberships
- Software
- Cloud storage
- Gaming subscriptions
- News services
- Delivery memberships
Canceling subscriptions you no longer use can create recurring savings without significantly changing your lifestyle.
7. Cook More Meals at Home
Eating at restaurants and ordering food regularly can become expensive.
Cooking at home gives you greater control over ingredients and spending.
You do not have to prepare complicated meals.
Planning a few simple meals each week and buying ingredients in advance can reduce unnecessary food spending.
You can still enjoy restaurants and takeout while making them occasional rather than automatic expenses.
8. Compare Prices Before Buying
Prices can vary significantly between stores and online platforms.
Before making a larger purchase, compare prices from multiple sellers.
This is particularly useful for:
- Electronics
- Appliances
- Travel
- Insurance
- Internet services
- Furniture
- Clothing
Price comparison can help you avoid paying more simply because you purchased from the first seller you found.
9. Avoid Impulse Purchases
Online shopping has made impulse purchases easier than ever.
A useful strategy is to wait before buying something that was not part of your original plan.
For smaller purchases, waiting a day may be enough.
For expensive purchases, consider waiting several days or longer.
If you still want the item after the waiting period and it fits your budget, you can make a more deliberate decision.
10. Use a Shopping List
Shopping without a plan can lead to unnecessary purchases.
Create a list before going to a supermarket or placing an online order.
Try to stick to the list unless something genuinely necessary comes up.
Meal planning can make grocery shopping even more efficient because you know exactly what ingredients you need.
11. Reduce Unnecessary Fees
Small fees can gradually reduce your available money.
Review your bank accounts, financial services and recurring payments for charges you may be able to avoid.
Depending on your situation, these could include:
- ATM fees
- Late payment fees
- Unused account fees
- Delivery charges
- Foreign transaction fees
Understanding the fee structure of the services you use can help you avoid unnecessary costs.
12. Be Careful With Credit Card Spending
Credit cards can be useful financial tools, but spending more than you can comfortably repay can lead to expensive interest charges.
Try to treat your credit limit as a payment facility rather than additional income.
Before making a purchase, consider whether you could afford the expense without relying on future income.
If you carry a balance, understanding the interest rate and repayment terms is particularly important.
13. Reduce Energy Consumption
Household energy costs can sometimes be reduced through simple changes.
Depending on where you live and your home setup, consider:
- Turning off unused lights
- Using energy-efficient lighting
- Adjusting heating or cooling settings
- Unplugging devices that are not needed
- Using energy-efficient appliances
- Improving insulation where practical
The potential savings vary by household, climate and energy prices.
14. Buy Quality When It Matters
Saving money does not always mean choosing the cheapest option.
A very inexpensive product may need to be replaced sooner, potentially costing more over time.
For products that you use frequently, consider durability, warranty, repairability and total cost of ownership.
The goal is not always to spend less today.
It is to make purchases that provide reasonable value over their useful life.
15. Set Specific Savings Goals
Saving without a goal can be difficult to maintain.
Instead of simply saying:
“I want to save more money.”
Create a specific target.
For example:
“I want to save $2,000 for an emergency fund.”
or:
“I want to save $5,000 for a future trip.”
A specific goal gives you something measurable to work toward.
You can then divide the target into smaller monthly or weekly amounts.
How to Save Money on a Low Income
Saving can be particularly difficult when most of your income already goes toward essential expenses.
In this situation, focus on realistic changes rather than trying to eliminate every discretionary expense.
Start with:
- Tracking expenses
- Reducing unnecessary subscriptions
- Comparing essential bills
- Planning meals
- Avoiding high-interest debt
- Setting aside even a small amount regularly
If expenses are already close to income, increasing income may be as important as reducing spending.
This could involve additional work, freelancing, selling unused items or developing skills that can increase earning potential.
How to Save Money Without Feeling Miserable
Extreme budgeting is difficult to maintain.
If you remove every activity you enjoy, you may eventually abandon the plan altogether.
A better approach is to prioritize.
Choose the expenses that provide the most value to you and reduce spending in areas that matter less.
For example, someone might choose to continue dining out once a week while reducing unnecessary online shopping.
The best savings strategy is one that you can maintain for a long time.
Where Should You Keep Your Savings?
The right place for savings depends on the purpose of the money and your circumstances.
Short-term emergency savings generally need to be accessible and relatively stable.
Longer-term money may have different considerations.
Before choosing a savings or investment product, understand factors such as:
- Accessibility
- Interest or potential return
- Fees
- Risk
- Taxes
- Withdrawal conditions
Savings and investments are not the same thing. Investments can lose value, while traditional savings products may offer different levels of protection depending on the country and institution.
How Long Does It Take to Build Savings?
There is no universal timeline.
It depends on:
- Income
- Expenses
- Savings rate
- Debt
- Financial goals
- Unexpected costs
Someone who saves a large percentage of their income may reach a goal quickly, while another person may need much longer.
What matters most is creating a consistent system and adjusting it as your financial situation changes.
A Simple Money-Saving Routine
A simple monthly routine can help keep your finances organized.
At the beginning of the month:
Set your spending and savings targets.
During the month:
Track expenses and avoid unnecessary purchases.
At the end of the month:
Review what you actually spent.
Then ask:
- Where did I overspend?
- What worked well?
- What can I change next month?
- Did I reach my savings target?
Repeating this process can help you gradually improve your financial habits.
Final Thoughts
Saving money does not require a perfect financial plan.
It starts with understanding your spending and making practical changes that you can maintain.
Creating a budget, tracking expenses, reducing unnecessary subscriptions, avoiding impulse purchases and automating savings can all help you build better financial habits.
The most important step is to start.
Even small improvements can become meaningful over time when they are repeated consistently.
Disclaimer: This article is provided for general educational and informational purposes only. It is not financial, investment, tax or legal advice. Personal financial decisions should be based on your individual circumstances and, where appropriate, advice from a qualified professional.