
What Is Compound Interest? How It Works Explained
Compound interest is one of the most important concepts in personal finance.
It can help savings grow over time, increase the cost of certain debts, and make starting early particularly valuable when building long-term wealth.
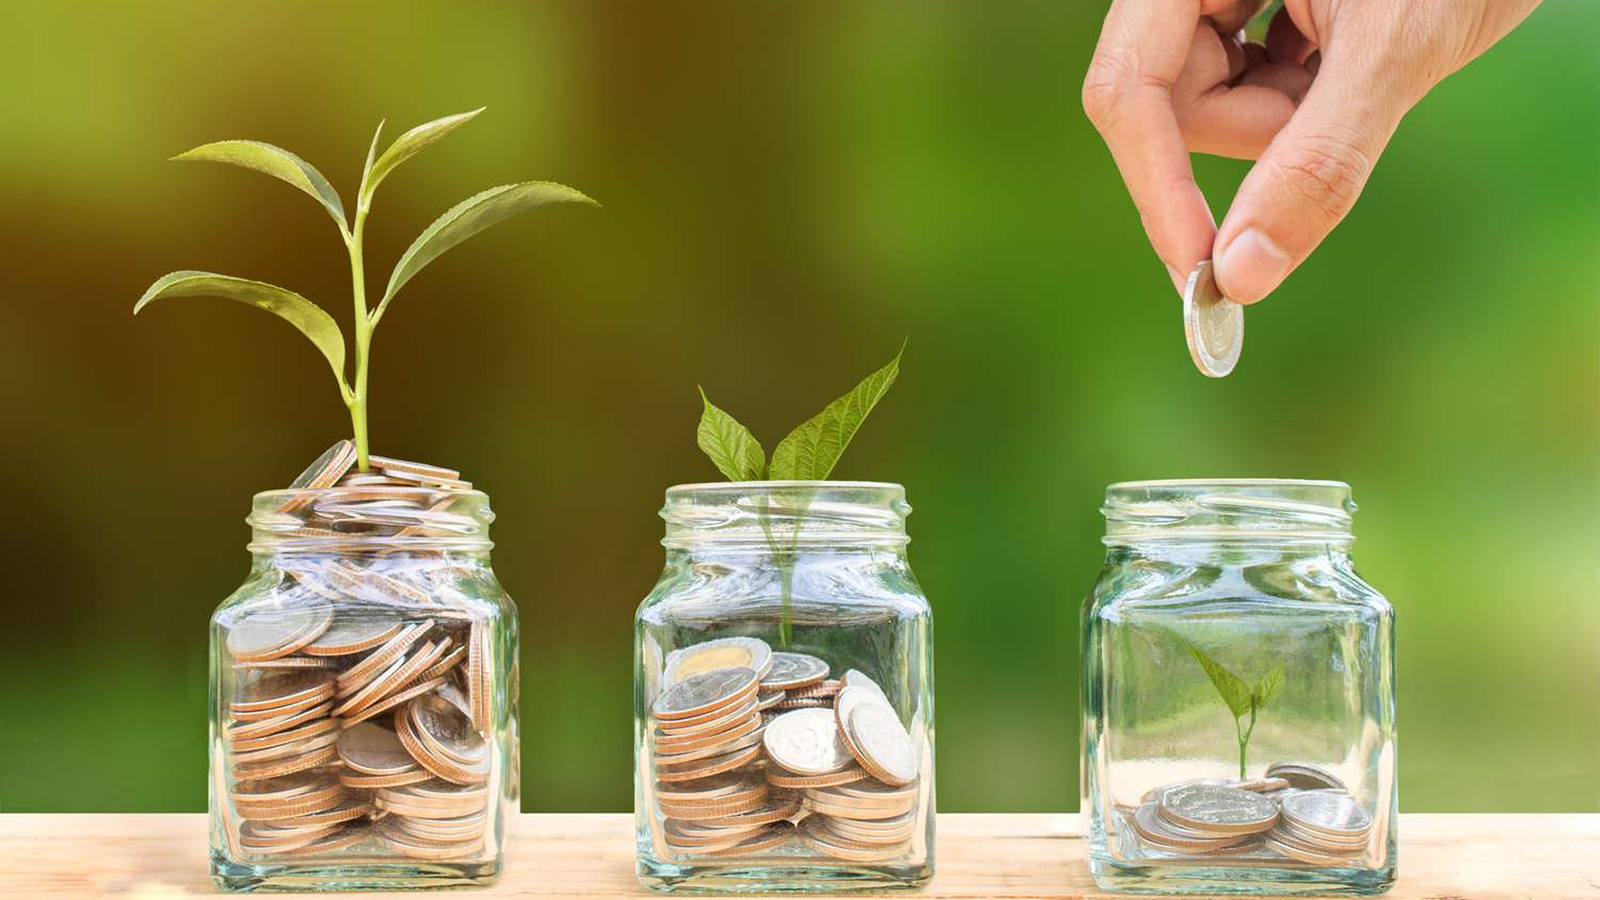
The basic idea is simple: you can earn interest not only on your original money, but also on interest that has already been added to it.
But how does that actually work?
What Is Compound Interest?
Compound interest is interest calculated on both the original amount of money and the interest accumulated from previous periods.
Suppose you deposit money into an account that earns interest.
With simple interest, interest is calculated only on the original amount.
With compound interest, previously earned interest can become part of the balance on which future interest is calculated.
Over time, this can create a compounding effect.
A Simple Example of Compound Interest
Imagine you invest $1,000 and earn 10% interest per year.
After the first year:
$1,000 + $100 interest = $1,100
During the second year, the 10% interest is calculated on $1,100 rather than only the original $1,000.
That produces:
$110 interest
The balance becomes:
$1,210
In the third year, interest is calculated on $1,210.
The balance continues to grow as the interest itself begins generating additional interest.
This is the basic principle of compounding.
Simple Interest vs Compound Interest
The difference becomes clearer when the two methods are compared.
| Feature | Simple Interest | Compound Interest |
|---|---|---|
| Interest calculated on | Original principal | Principal + accumulated interest |
| Growth | More linear | Can accelerate over time |
| Previous interest earns interest | No | Yes |
| Long-term effect | Usually smaller | Can be significantly larger |
The difference may appear small over a short period, but it can become much more noticeable over many years.
How Does Compound Interest Work?
Compound interest involves several important factors:
Principal
The principal is the original amount of money.
For example, if you deposit $5,000, your starting principal is $5,000.
Interest Rate
The interest rate determines how quickly the money grows.
A higher rate can result in faster growth, assuming other factors remain the same.
Time
Time is one of the most important factors in compounding.
The longer money remains invested or saved, the more opportunities there are for interest to compound.
Compounding Frequency
Interest can be compounded at different intervals.
Common frequencies include:
- Annually
- Semi-annually
- Quarterly
- Monthly
- Daily
More frequent compounding can produce a somewhat different result when the stated rate and other conditions are comparable.
The Compound Interest Formula
A commonly used compound interest formula is:
A = P(1 + r/n)^(nt)
Where:
- A = final amount
- P = principal
- r = annual interest rate expressed as a decimal
- n = number of compounding periods per year
- t = number of years
For example, an annual interest rate of 5% would be represented as 0.05 in the formula.
The formula allows you to estimate how an amount can grow when interest compounds over time.
Why Time Matters So Much
Compounding becomes increasingly powerful as time passes.
Consider two people who invest the same amount of money at the same rate.
One starts significantly earlier and leaves the money invested for a longer period.
The person who started earlier may accumulate substantially more because their money has had more time to generate returns, which can then generate additional returns.
This is one reason long-term investing often emphasizes starting early rather than waiting for the “perfect” time.
Adding Money Regularly
Compounding can become even more powerful when you continue adding money to an account or investment.
For example, instead of investing $5,000 once, you might contribute a fixed amount every month.
Each contribution has the opportunity to participate in future growth.
Over long periods, regular contributions plus compounding can make a significant difference.
However, actual investment returns are not guaranteed, and market-based investments can rise or fall.
Where Can Compound Interest Apply?
Compound interest can appear in several areas of personal finance.
Savings Accounts
Some savings products pay interest that can compound over time.
The actual rate, frequency, and terms depend on the financial institution and account.
Fixed Deposits and Similar Products
Certain deposit products may calculate or pay interest according to compounding arrangements.
The specific terms depend on the product.
Investments
Long-term investments can benefit from the general concept of compounding when returns remain invested and generate future returns.
However, investment returns are not the same as guaranteed bank interest.
Markets can go down as well as up.
Debt
Compounding can also work against you.
Certain forms of debt can accumulate interest and other charges over time.
If balances remain unpaid, the amount owed can increase significantly depending on the terms of the debt.
Compound Interest on Debt
The same mathematical concept that can help savings grow can make debt more expensive.
Imagine you have an unpaid balance that accumulates interest.
If interest is added to the amount owed and future interest is then calculated on the increased balance, the debt can grow faster.
This is one reason high-interest debt can become difficult to manage when payments are delayed.
Why Starting Early Can Matter
Consider two hypothetical investors.
Investor A starts investing at age 25.
Investor B starts at age 35.
Even if both eventually invest substantial amounts, Investor A has an additional decade for potential growth to compound.
This does not mean starting later is pointless.
It simply illustrates the mathematical advantage of giving money more time to potentially grow.
Does Compound Interest Guarantee Wealth?
No.
Compound interest is a mathematical process, not a guarantee of investment success.
For savings accounts with stated interest rates, the growth may be relatively predictable according to the account terms.
For investments, returns can vary.
An investment that grows in one year may decline in another.
Fees, taxes, inflation, and market performance can also affect the actual result.
Compound Interest and Inflation
An important consideration is inflation.
Suppose your savings earn 4% annually while prices rise by 5%.
Although your account balance has increased in nominal terms, your purchasing power may not have increased by the same amount.
This is why evaluating long-term financial growth often requires considering both investment returns and inflation.
How to Make Compounding Work in Your Favor
There are several practical habits that can help you benefit from compounding.
Start Early
Starting earlier gives your money more time to potentially grow.
Invest or Save Consistently
Regular contributions can increase the amount of money participating in future growth.
Reinvest Returns
When appropriate, keeping earnings invested allows them to potentially generate additional returns.
Avoid Unnecessary High-Cost Debt
Compounding can work against you when interest accumulates on debt.
Reducing expensive debt can therefore be an important part of financial planning.
Be Patient
Compounding is generally more powerful over long periods than short ones.
Trying to become wealthy quickly can encourage unnecessary risk.
A Hypothetical Long-Term Example
Imagine investing $10,000 at an assumed annual return of 7%, with the returns remaining invested.
After approximately:
- 10 years: $19,672
- 20 years: $38,697
- 30 years: $76,123
These figures are mathematical illustrations assuming a constant 7% annual return and no additional contributions, taxes, or fees.
Actual investment results can be very different because market returns fluctuate.
The example demonstrates the effect of allowing returns to remain invested over a long period.
Compound Interest Isn’t Only About Money
The principle of compounding can be useful as a broader way to understand long-term growth.
Small improvements repeated consistently can create meaningful results over time.
The same idea can apply to:
- Saving
- Investing
- Learning
- Building skills
- Growing a business
- Developing habits
The underlying idea is that progress can build upon previous progress.
Common Mistakes About Compound Interest
Thinking It Works Overnight
Compounding is generally most powerful over longer periods.
Ignoring Fees
Investment and account fees can reduce the amount available for future growth.
Confusing Returns With Guaranteed Interest
Market investment returns are not guaranteed simply because they may compound.
Waiting Too Long to Start
Many people focus on finding the highest possible return while overlooking the value of giving their money more time.
Taking Excessive Risk
The desire to accelerate growth can lead people toward investments that do not match their risk tolerance.
Higher potential returns generally come with higher risk.
Final Thoughts
Compound interest is the process through which money can generate returns, and those returns can then contribute to future growth.
Its biggest advantage is time.
Starting early, contributing consistently, keeping returns invested, and avoiding unnecessary high-interest debt can all help you understand and use the power of compounding more effectively.
The numbers may look modest at first, but over many years, the difference can become substantial.
Financial Disclaimer: This article is for general educational purposes only and does not constitute financial, investment, tax, or legal advice. Investment returns are not guaranteed, and you should consider your own financial circumstances and risk tolerance before making financial decisions.